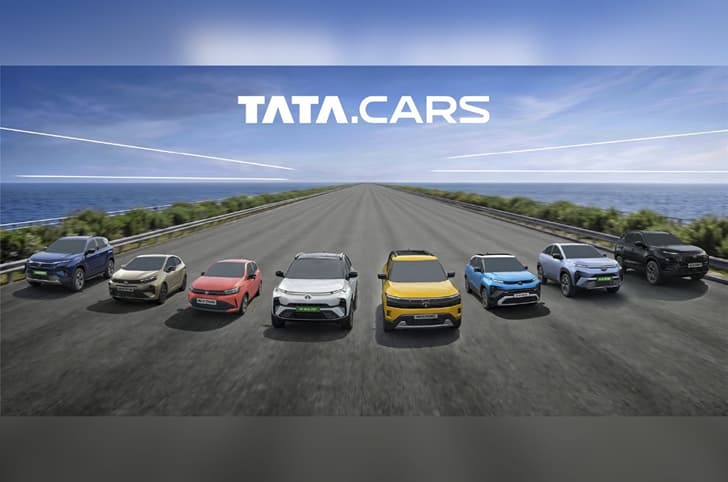

Tata PV sold 7.44 lakh units in its first post-demerger year (Oct 2025–Sep 2026), growing 35% and capturing 14.1% market share, driven by the Nexon, Punch, Sierra, and surging CNG and EV demand.
How Tata's Passenger Vehicle Business Grew 35% in 2026: What This Means for Buyers Comparing Brands
Tata Motors' passenger vehicle (PV) division is defined as the standalone entity that separated from the company's commercial vehicle (CV) business on October 1, 2025, and in its very first year of independent operation it grew 35% to 7.44 lakh domestic units — a pace that nearly outran the industry's own strong ~22% growth rate. For anyone currently shopping for a car in India, that number matters beyond the headline: it signals which brand is expanding its product range fastest, where after-sales infrastructure is being built, and how pricing pressure from rivals is likely to play out over the next few years.
Below is a snapshot of how India's top three passenger vehicle brands compare on the metrics that matter most to a buyer right now.
| Metric | Tata Motors PV | Maruti Suzuki | Mahindra & Mahindra |
|---|---|---|---|
| Domestic PV sales (Oct 2025–Sep 2026) | ~7.44 lakh units | ~21 lakh units (est. full-year leader) | ~7–8 lakh units (est.) |
| Market share | 14.1% | ~41% (est.) | ~13–14% (est.) |
| YoY sales growth | 35% | ~10–12% (est.) | ~18–20% (est.) |
| Top-selling model | Nexon (2.38 lakh) | Wagon R / Baleno | Scorpio-N / XUV 3XO |
| Alternative fuel mix (EV + CNG) | 44% of volumes | CNG-heavy; EV nascent | Petrol/diesel dominant; EV growing |
| FY31 volume target | 12 lakh units/year | Maintain ~40%+ share | 10 lakh+ units/year |
| Service network growth plan | 3× workshops vs 2× showrooms | Largest existing network in India | Expanding rapidly post-SUV boom |
| Key weakness for buyers | Supply constraints; quality perception still improving | Limited SUV depth at higher price points | Waiting periods on key models; fewer CNG options |
Figures for Maruti Suzuki and Mahindra are industry estimates; Tata figures are company-reported. Market share percentages are approximate.
What exactly happened with the Tata PV demerger, and why does it matter to a car buyer?
The demerger is defined as the formal legal and operational separation of Tata Motors' passenger vehicle business from its commercial vehicle (trucks, buses) operations, which came into effect on October 1, 2025. The listed entity — Tata Motors Passenger Vehicles Ltd. (NSE: TMPV) — now has its own balance sheet, its own board (chaired by N. Chandrasekaran, with Shailesh Chandra as MD & CEO), and its own capital allocation priorities focused entirely on cars and SUVs.
For a buyer, this matters in three practical ways. First, R&D spending no longer has to compete with truck platform investments — every rupee the PV division earns can go back into new car programmes. Second, the quality department now reports directly to Shailesh Chandra rather than to the manufacturing head, which is a structural change designed to catch problems earlier. Third, dealer incentive structures have been reweighted toward customer satisfaction scores, which should gradually improve the ownership experience — though Chandra himself admitted that "the perception will only change after three-four years."
Which Tata models drove the 35% growth, and what does that tell buyers about the lineup?
Two SUVs accounted for the bulk of the expansion. The Nexon sold 2.38 lakh units and the Punch sold 2.33 lakh units between October 2025 and September 2026, together representing roughly 63% of Tata's total domestic volumes. That concentration is both a strength and a vulnerability: the brand's fortunes remain heavily tied to two nameplates, even as it works to broaden the portfolio.
The Sierra stands out as the most significant new addition. Sales crossed 60,000 units between January and September 2026, despite supply being constrained as production was scaled up. The Sierra is also notable as one of the first Tata models developed with software and hardware tested together from an early stage — a process the company says will reduce the kind of over-the-air update dependency that frustrated some early EV owners.
The "15 product interventions" Tata counts over the past year include the updated Punch, Tiago, petrol versions of the Harrier and Safari, and the new Aeris (priced from approximately ₹5.30 lakh ex-showroom). That last model is significant because it plugs a gap in the entry hatchback segment where Maruti Suzuki's Alto K10 and Wagon R have historically dominated without serious Tata competition.
Tata's lineup now spans a wider price range than at any point in its recent history — from the Aeris at the entry end to the Sierra and Harrier petrol at the upper-mid segment. The risk is that spreading across so many launches simultaneously can dilute marketing support and dealer readiness, which is why Tata says it is now recalibrating launch timelines to give each model proper runway.
How big a role did the GST revision play, and is that tailwind still active?
The revised GST rates that took effect on September 22, 2025 — just nine days before the demerger — made cars more affordable across multiple segments and provided a demand surge that carried into the following quarters. Shailesh Chandra was candid about this: "We had not expected 35 percent," he said, acknowledging that the GST cut was a material tailwind.
Monthly bookings topped one lakh units more often than not during this period, and more than seven in ten bookings converted to retail sales. Tata crossed the 70,000-unit mark in a single month twice, and two of its four quarters exceeded two lakh units each.
A one-time GST revision is not a structural advantage. As that base effect normalises over the coming year, Tata's growth rate will almost certainly moderate. The company's own FY31 target of 12 lakh units per year implies a compound annual growth rate of roughly 8–10% from the current base — much more modest than the 35% headline. Buyers should not expect the same urgency of discounting or promotional pricing that characterised late 2025 and early 2026.
What does Tata's CNG push mean for buyers considering a Nexon CNG versus a Maruti Brezza CNG?
CNG is defined here as factory-fitted bi-fuel (petrol + CNG) powertrains that come with a manufacturer warranty, as opposed to aftermarket conversions. Tata's CNG volumes grew 31% to over 2.03 lakh units in the October 2025–September 2026 period, making it one of the fastest-growing CNG portfolios in the industry.
The Nexon CNG and Maruti Suzuki Brezza CNG are the two most directly comparable options in the compact SUV CNG space. Both are factory-fitted, both carry manufacturer warranties on the CNG system, and both target buyers doing high monthly mileage in cities with good CNG infrastructure (primarily Delhi-NCR, Mumbai, Pune, Ahmedabad, and Surat).
The Nexon CNG offers more boot space and a larger footprint, and benefits from Tata's 5-star Global NCAP safety rating — a genuine differentiator. The Brezza CNG draws on Maruti Suzuki's unmatched service network: the brand's workshops are present in virtually every district headquarters in India, which matters enormously for CNG buyers who may need more frequent servicing. Tata's service network, while growing rapidly (from 1.5 lakh vehicles per month in 2021 to six lakh per month now), is still catching up. If you live outside a Tier-1 city, the Brezza CNG's service accessibility advantage is real and should not be dismissed.
For buyers weighing these two options, our detailed guide on 5-star NCAP-rated SUVs under ₹15 lakh provides a broader safety-first shortlist.
Is Tata's quality perception improving, and should it affect your buying decision today?
The brand has acknowledged quality and after-sales perception as an ongoing challenge, and Chandra's own timeline — "three-four years" before perception meaningfully changes — is a remarkably candid admission from a sitting MD.
The structural changes are real: quality now reports to the top, software and hardware are integrated earlier in development (the Sierra being the first beneficiary), and a central software integration team is being built into a centre of excellence. Between April and June 2026, spare parts availability was a genuine problem for existing owners — Tata has since prioritised spare parts for existing customers even at the cost of new-car production, and claims fill rates are back to 85–86%. That is better, but not best-in-class.
Before buying a Nexon, Punch, or Harrier petrol, factor in whether there is a Tata authorised service centre within a reasonable distance of your home or workplace. The brand has addressed 26 of the 30 locations it flagged as service problem areas, but gaps remain. Dealer incentives are now weighted toward customer satisfaction, which is a positive structural signal — but it will take time to show up in owner forums and resale values.
What is Tata targeting by FY31, and how does that shape the competitive space for buyers?
Tata's stated ambition is defined as reaching over 12 lakh units per year by FY31 (financial year ending March 2031) with a 20% share of the Indian passenger vehicle market. To get there from 7.44 lakh units, the company plans over 20 product refreshes and six entirely new nameplates, including the Avinya — a model that will sit at the premium end of the petrol/hybrid spectrum.
Capacity constraints represent the most immediate bottleneck. Tata's own plants and their tier-2 and tier-3 suppliers are stretched thin, and the Sanand facility in Gujarat is expected to play a central role in adding volume. Exports have nearly doubled to around 12,000 units, helped by Tata's entry into South Africa, but export volumes remain a small fraction of the total.
Hyundai — which currently sits just behind Tata at the number-three position — has publicly stated its intention to reclaim the number-two spot by 2028–29, backed by a ₹7,000 crore investment in its Talegaon plant and a pipeline of 26 new models. Mahindra is similarly aggressive in the SUV space. The competitive window Tata currently enjoys — being the only brand with both a credible CNG SUV portfolio and a dominant EV position — will narrow as rivals invest.
For buyers, this competitive intensity is good news: it means more product choice, more aggressive pricing, and faster feature upgrades across all brands over the next three to five years.
How does Tata's EV dominance affect buyers who are considering petrol or CNG cars?
Tata's EV sales grew 84% to 1.3 lakh units, and the brand claims a 42% share of India's passenger EV market. This article's scope is petrol, diesel, and CNG cars, so the EV numbers are cited as market context rather than a buying recommendation.
Because product development for all powertrain categories now falls under a single chief product officer — with each powertrain getting its own dedicated team — the petrol and CNG programmes are no longer starved of engineering resources by EV investment. Shailesh Chandra explicitly noted that EV and non-EV competitors are different sets of rivals, and that the product organisation reflects this.
The Nexon petrol and Nexon CNG are not being treated as legacy products being wound down in favour of the Nexon EV. They are active development programmes with their own roadmaps. The same logic applies to the Punch CNG and the petrol Harrier and Safari, both of which were launched as part of the "15 product interventions" in the past year.
Buyers who are firmly in the petrol or CNG camp should feel confident that Tata's investment in those powertrains is not being cannibalised by its EV ambitions — at least for the foreseeable future.
Should the service network expansion change how you evaluate Tata versus Maruti Suzuki today?
Maruti Suzuki's service network is defined as the largest in the Indian passenger vehicle industry by outlet count, and it remains the single biggest reason many buyers — particularly in Tier-2 and Tier-3 cities — default to the brand even when a Tata or Hyundai product might better suit their needs on paper.
Tata's workshops now handle six lakh vehicles per month, up from 1.5 lakh in 2021 — a 4× increase in five years. Chandra's commitment to tripling service centres while only doubling showrooms signals that the brand understands where it has lost customers. But tripling from a smaller base still leaves a gap versus Maruti's decades-long head start.
Before committing to a Tata purchase, check the nearest authorised service centre's distance from your home, its Google reviews from the past six months (not older), and whether it handles the specific model you are buying. The Sierra, for instance, is a newer model whose service technicians may be less familiar with it than with the Nexon or Punch. This is not a reason to avoid the Sierra — it is a reason to ask your dealer specifically about technician training for that model.
For safety-conscious buyers comparing Tata's lineup against rivals, our guide to SUVs with 6 airbags under ₹25 lakh is a useful cross-brand reference.
What is the bottom line for a buyer comparing Tata against Maruti Suzuki or Mahindra right now?
The 35% growth figure is a business metric, but it has direct buying implications. Here is what it actually translates to:
Product breadth: Tata now has a credible answer in more segments than it did two years ago — entry hatchback (Aeris), micro-SUV (Punch), compact SUV (Nexon), mid-size SUV (Sierra, Harrier petrol, Safari petrol). Maruti Suzuki still leads in hatchbacks and entry sedans; Mahindra leads in body-on-frame and premium SUVs.
Powertrain choice: Tata is the only brand offering factory-fitted CNG across multiple SUV body styles while simultaneously leading the EV market. Maruti Suzuki has a broader CNG hatchback range but fewer CNG SUVs. Mahindra's CNG portfolio is thinner.
Safety: Tata's 5-star NCAP ratings on the Nexon and Punch are genuine competitive advantages. Maruti Suzuki has improved significantly with recent models, but the Wagon R and Alto K10 — its volume leaders — carry lower ratings.
After-sales: Maruti Suzuki wins on network depth and parts availability, particularly outside major cities. Tata is improving but is still 3–4 years away from matching that consistency by its own admission.
Waiting periods: Supply constraints at Tata mean some models, particularly the Sierra, carry waiting periods. Maruti Suzuki's production scale means shorter waits on most models.
Resale value: Maruti Suzuki historically commands the best resale values in India. Tata's resale has improved as volumes and brand perception have grown, but the gap has not closed entirely.
The decision ultimately comes down to what you are optimising for. If you prioritise safety ratings, powertrain variety (especially CNG SUVs), and a rapidly expanding product range, Tata's current momentum makes it a compelling choice. If you prioritise after-sales peace of mind, resale value certainty, and the widest possible service network, Maruti Suzuki's structural advantages have not disappeared — they have simply narrowed.
Mahindra sits in a different sweet spot: if you want a petrol or diesel SUV with strong road presence and are willing to wait for delivery, models like the Scorpio-N and XUV 3XO remain formidable. But Mahindra's CNG options are limited and its EV ambitions are still developing.
Tata's 35% growth year is real, significant, and buyer-relevant. It is also, in part, a one-time GST tailwind on top of a structural improvement. The brand's trajectory is clearly upward — but the gap between ambition and execution on quality and service will define whether it can hold the number-two position it has just claimed.
Sources
- Tata's passenger vehicle business grows 35 percent in first year after demerger | Autocar India
- Hyundai bets on expansion; hopes to return to No 2 position in PV sales by 2028-29 | Economic Times
- Tata Motors Passenger Vehicles Ltd. Share Price | ET Money
- Tata Motors official website
- 5-Star Bharat NCAP-Rated SUVs Under Rs 15 Lakh in India (2026) | AutoindexIndia
- 9 Best SUVs With 6 Airbags Under Rs 25 Lakh in India (2026) | AutoindexIndia